Most Malaysians starting out in their property journey avoid subsale houses. New developments often dubbed “under-construction” or “developer units” come wrapped in neat marketing packages: free legal fees, zero downpayment, booking fees as low as RM1,000, and of course shiny show units.
Subsale properties? They often require significant upfront capital, a load of patience, and the mental energy to deal with moving parts far beyond your control.
So, what does it actually take to buy a subsale house in Malaysia? Are the popular property site calculators accurate? Are AI estimations accurate? Spoiler: Not really!
Let’s go through the true cost, real-world numbers, and step-by-step reality of buying a pre-owned home in Malaysia.
Why Even Buy a Subsale House?
Every property guru will preach “LOCATION, LOCATION, LOCATION.” And they aren’t wrong.
For a residential property, location heavily drives its real-world valuation. Subsale homes generally win hands-down here because they are situated in established, mature neighborhoods. You get actual built-in amenities: existing schools, established highways, functioning LRT/MRT lines, and local eateries, not a developer’s promise of what might exist in 2028. Plus, you get to inspect the actual unit, check the neighbors, and asses the upkeep of the building or neighborhood before putting a single Sen down.
Step 1: Finding the Home & Negotiating
Once you have a target area and spot a home for sale, your first job isn’t making an offer, it’s running the numbers.
- Check Local Listings & Historical Data: Browse comparable listings nearby and check recent transaction data from the National Property Information Centre (NAPIC) or real estate platforms. This gives you a baseline of what banks are “likely” to value the property at.
- Get a Professional Valuation (Optional, but STRONGLY ENCOURAGED): Before putting down a deposit, consulting an independent banker, valuer and defect check can save you tens of thousands. If a seller wants RM600,000 but the bank values it at RM530,000, you will need to bridge that RM70,000 “valuation gap” out of your own pocket or if the house has a lot of repairs needed, it will save you the headache later on.
- Negotiate: Talk to the seller (vendor) or their listing agent. Ask questions about property age, reason for selling, maintenance issues, and past renovations. Always start with a counter-offer way below asking.
Step 2: The Letter of Offer & Earnest Deposit
Once an offer is accepted, you will sign a Letter of Offer (also known as the Booking Form) and pay an Earnest Deposit.
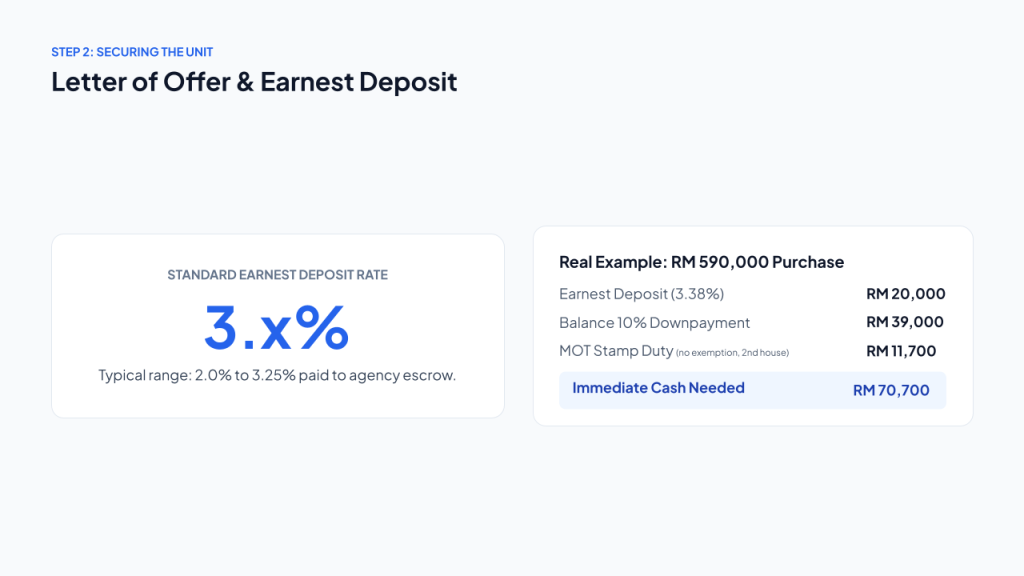
- Earnest Deposit: Usually 2.x% to 3.x% of the purchase price, paid directly to the real estate agency’s escrow account (never directly to the seller’s personal bank account!).
- Real Example: On my first property, I paid a 3.18% earnest deposit. On my second, it was 3.39%.
For a RM590,000 house, a 3.39% earnest deposit comes out to around RM20,000. The remaining RM39,000 of your 10% downpayment is paid to the seller’s lawyer upon signing the Sale and Purchase Agreement (SPA). This is cold hard cash, unless you take a 100% loan and the vendors are aware of it.
At this stage, you are RM20,000 out of pocket, and the agent will help coordinate the next two critical paths: Lawyers and Financing.
Step 3: Legal Fees, Stamp Duty & The Hidden Costs
This is where online property calculators and general AI estimations usually fall short.
Most online guides cite the standard scale rates under the Solicitors’ Remuneration Order (SRO) to tell you how much an SPA lawyer will cost. While those scale fees exist, they don’t give you the full picture.
Under Malaysia’s Solicitors’ Remuneration Order 2023, the scale fee for a RM590,000 subsale transaction is:
- First RM500,000: 1.25% = RM6,250
- Remaining RM90,000: 1% = RM900
Totaling: RM 7,150
In practice:
- Lawyers often quote discounted scale fees, BUT…
- They add line items for disbursements and administrative tasks (land searches, bankruptcy checks, CHKT/RPGT forms, registration fees, affirmation fees, courier fees, and stamping charges).
- You also have to pay MOT (Memorandum of Transfer) Stamp Duty to the government to register ownership under your name.
Actual Breakdown for a financed RM590,000 Subsale Purchase
Here is how the cash outlay looks in the real world for a RM590,000 house that is financed:
| Expense Item | Real-World Estimated Cost | Notes |
| Purchase Price | RM 590,000 | Agreed transaction price |
| 10% Total Downpayment | RM 59,000 | RM20k earnest deposit + RM39k upon SPA signing |
| SPA Lawyer Fee + Disbursements | RM 11,000 | Includes scale fee, search fees, CHKT, and misc. disbursements |
| MOT Stamp Duty | RM 11,700 | Based on tiered MOT stamp duty rates, cash. |
| Loan Legal Fee | RM 11,494 | Lawyer fee for preparing bank loan agreement |
| Loan Stamp Duty | RM 2,886.89 | 0.5% of the total loan amount |
| Bank Valuation Fee | RM 2,000 | Fee charged by bank-appointed valuer |
| MRTA / MRTT Insurance | RM 16,878.70 | Mortgage insurance (varies by age, health, and loan tenure) |
First-Time Homebuyer Note: First-time buyers in Malaysia qualify for full MOT stamp duty exemptions for properties priced up to RM500,000, and partial discounts for properties up to RM750,000 under recent government budget initiatives. If you qualify, your MOT costs will drop significantly!
What you need to set aside usually, the upfront deposits and MOT stamp duty if you are ineligible for exemptions.
A Warning on SPA Legal Budgets
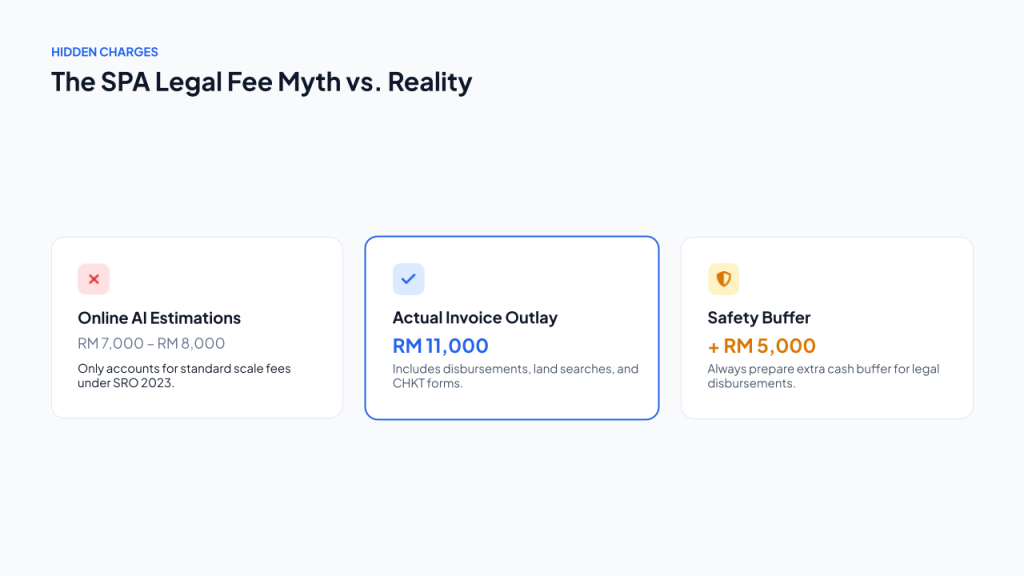
Most online articles tell buyers to budget RM7,000–RM8,000 for legal fees on a RM600k property. In reality, once you factor in disbursements, land searches, and administrative costs, you should always add a buffer of RM5,000 from the basic quote if you aren’t financing legal fees.
Can You Finance Legal Fees & Insurance into the Loan?
Yes and no. Banks typically only allow you to finance Loan Legal Fees, Valuation Fees, and MRTA/MRTT into the mortgage. However, some banks offer slightly higher margin packages (e.g., 90% + 5% extra margin) which can absorb some of these charges, freeing up cash for your SPA legal fees.
You usually cannot finance your MOT stamp duty, so do prepare some cash to pay that if you do not have an exemption, unless the bank approves a higher margin, in which you may be able to get some cash back.
In my case, after absorbing eligible fees into the mortgage, the total financed loan amount came out to RM 577,378.70.
Home: RM 531000.00
Legal fees: RM 27500.00
MRTA: 16,878.70
Valuation: RM 2000.00
Total: RM 577,378.70
Step 4: The Real Timeline
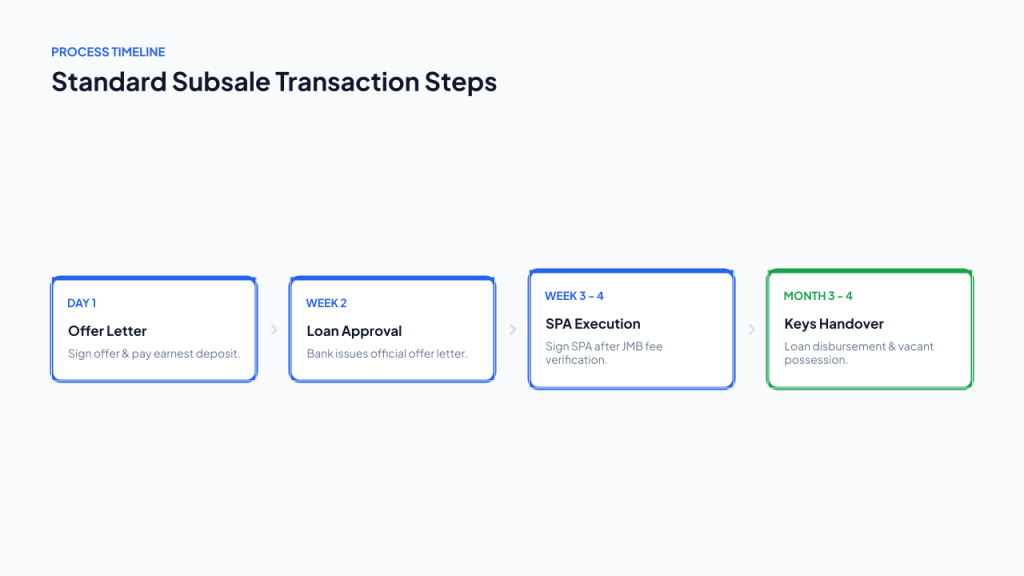
How long does it take from signing the booking form to holding the keys (Vacant Possession)?
[Day 1] Letter of Offer Signed & Earnest Deposit Paid
   │
   ├──► [Weeks 1 – 2] Apply & Secure Loan Offer Letter
   │
   ├──► [Weeks 2 – 4] Lawyers Draft SPA & Perform Searches
   │
   └──► [Month 1 – 1.5] Sign SPA, Loan Agreement & Pay Remaining Downpayment
         │
         └──► [Months 3 – 4] State Consent (if applicable), Full Disbursement & Vacant Possession!
- Days 1 – 14: Sign Letter of Offer, pay earnest deposit, submit income documents to banks/mortgage brokers, and obtain your Bank Loan Offer Letter.
- Weeks 2 – 4: The lawyer drafts the SPA. This timeline depends on how fast the vendor’s lawyer supplies documents and how quickly property management (JMB/MC) confirms there are no outstanding maintenance bills.
- Months 1.5 – 4: Sign the SPA and Loan Agreement, settle remaining cash balances, wait for bank disbursements, and receive keys.
The Master Title Trap ⚠️
The 3–4 month timeline applies to standard Individual Title or Strata Title properties. If you are buying a unit that is still under a Master Title (where developer subdivision hasn’t happened yet, or developer liquidations are involved, think old projects like Putra Perdana), brace yourself. Master Title subsale transactions require developer consent, direct liquidator approvals, or court orders, extending the process anywhere from 6 to 12+ months.
Summary Checklist Before You Buy Subsale
- [ ] Verify Bank Valuation: Ensure the bank values the unit at or above the purchase price.
- [ ] Prepare Cash Buffers: Have 10% downpayment cash + RM15,000–RM20,000 extra cash on hand for SPA fees, MOT, and unexpected disbursements.
- [ ] Check Title Status: Confirm if the property is Individual, Strata, or Master Title before signing.
- [ ] Inspect Maintenance & Dues: Ensure the vendor has paid off all outstanding utility bills, assessment taxes (Cukai Taksiran), quit rent (Cukai Tanah), and JMB maintenance fees.
Looking to plan your home purchase budget seamlessly? Use Teddy App to track your savings goals, manage upfront homeownership expenses, and keep your financial journey on track. Use the built in calculator to get a realistic estimation when buying a subsale home!